Car-for-Cash Loans: Key Considerations for a Smooth Application Process
February 19, 2025
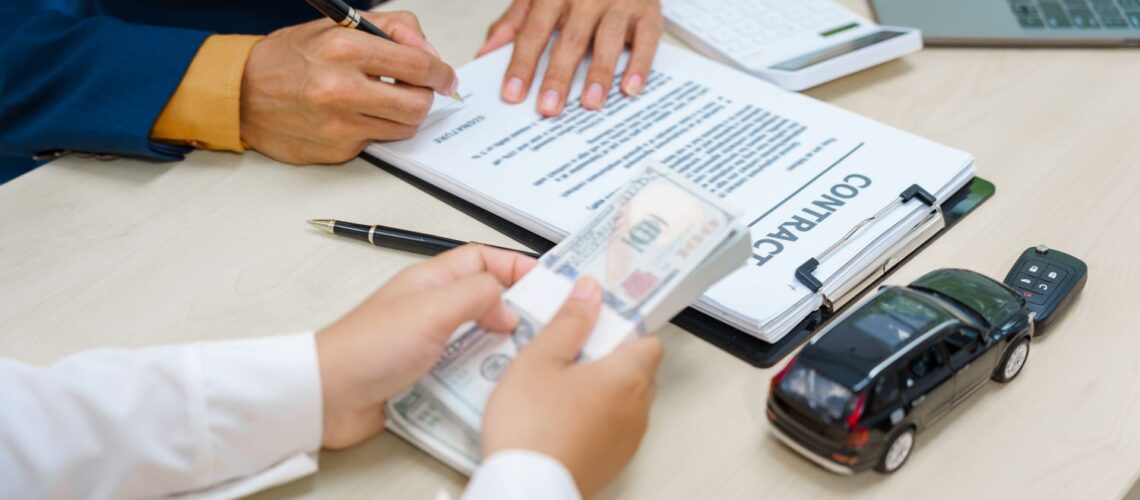
Car-for-cash loans, also known as auto equity loans or title loans, allow individuals to borrow money using their vehicle as collateral. This type of financing can be a quick way to access cash, especially in emergencies. However, the application process can be complex, and there are several factors to consider to ensure a smooth experience. This guide will outline the key considerations for obtaining a car-for-cash loan and provide tips for a successful application process.
1. Understanding Car-for-Cash Loans
A. What is a Car-for-Cash Loan?
A car-for-cash loan allows borrowers to leverage the equity in their vehicle to secure a loan. The lender holds the title to the vehicle until the loan is repaid, and the borrower can typically continue driving the car during the loan term.
B. Types of Car-for-Cash Loans
- Title Loans: These loans are based on the value of your vehicle’s title. They often have higher interest rates and shorter repayment terms.
- Auto Equity Loans: These loans allow you to borrow against the equity in your vehicle, usually with more favorable terms compared to title loans.
2. Key Considerations Before Applying
A. Vehicle Value
Determine the current market value of your vehicle before applying for a car-for-cash loan. Several online resources, such as Kelley Blue Book or Edmunds, can help you estimate your car’s worth. The loan amount is typically based on this value, so having an accurate assessment is crucial.
B. Loan Terms and Interest Rates
Research and compare loan terms and interest rates from different lenders. Car-for-cash loans often come with higher interest rates than traditional loans, so it’s essential to understand the total cost of borrowing and ensure it fits within your budget.
C. Repayment Terms
Consider the repayment terms offered by the lender. Understand the length of the loan, monthly payment amounts, and any penalties for late payments. A shorter loan term may result in higher monthly payments but can save you money on interest in the long run.
D. Lender Reputation
Choose a reputable lender with positive reviews and a transparent lending process. Research their practices and read customer testimonials to ensure that you are working with a trustworthy institution.
3. Preparing for the Application Process
A. Required Documentation
Gather the necessary documentation before starting the application process. Common requirements include:
- Vehicle Title: Proof of ownership demonstrating that you hold the title to the vehicle.
- Identification: A government-issued ID (like a driver’s license) to verify your identity.
- Proof of Income: Recent pay stubs or bank statements to demonstrate your ability to repay the loan.
- Insurance Information: Proof of insurance coverage on the vehicle may be required by the lender.
B. Assess Your Financial Situation
Before applying, evaluate your financial situation to determine how much you need to borrow and if you can comfortably afford the monthly payments. This assessment will help you avoid taking on more debt than you can manage.
4. The Application Process
A. Online vs. In-Person Applications
Many lenders offer online applications, which can be convenient and save time. However, if you prefer a more personal approach, consider visiting a local branch to discuss your options with a representative.
B. Provide Accurate Information
Ensure that all the information you provide during the application process is accurate and complete. Any discrepancies can delay approval or lead to complications down the line.
C. Review the Terms Carefully
Before signing any agreements, carefully review the terms and conditions of the loan. Pay attention to interest rates, fees, and repayment schedules to avoid any surprises.
5. Managing the Loan
A. Make Timely Payments
To avoid penalties and protect your credit score, make your loan payments on time. Set up reminders or automatic payments to help you stay on track.
B. Communicate with Your Lender
If you encounter financial difficulties and anticipate trouble making payments, communicate with your lender as soon as possible. They may offer options such as payment deferrals or restructuring the loan.
C. Keep Track of Your Vehicle’s Condition
Since your vehicle is collateral for the loan, maintaining its condition is essential. Regular maintenance can help preserve its value and prevent potential issues that could arise during the loan term.
Conclusion
Car-for-cash loans can be a viable solution for individuals needing quick access to cash, but understanding the process and key considerations is crucial for a smooth application. By assessing your vehicle’s value, researching lenders, preparing necessary documentation, and managing the loan responsibly, you can navigate the world of car-for-cash loans effectively. Remember, making informed decisions will help ensure that you are comfortable with your financial commitments and can successfully leverage your vehicle’s equity for your needs.
Recent Comments